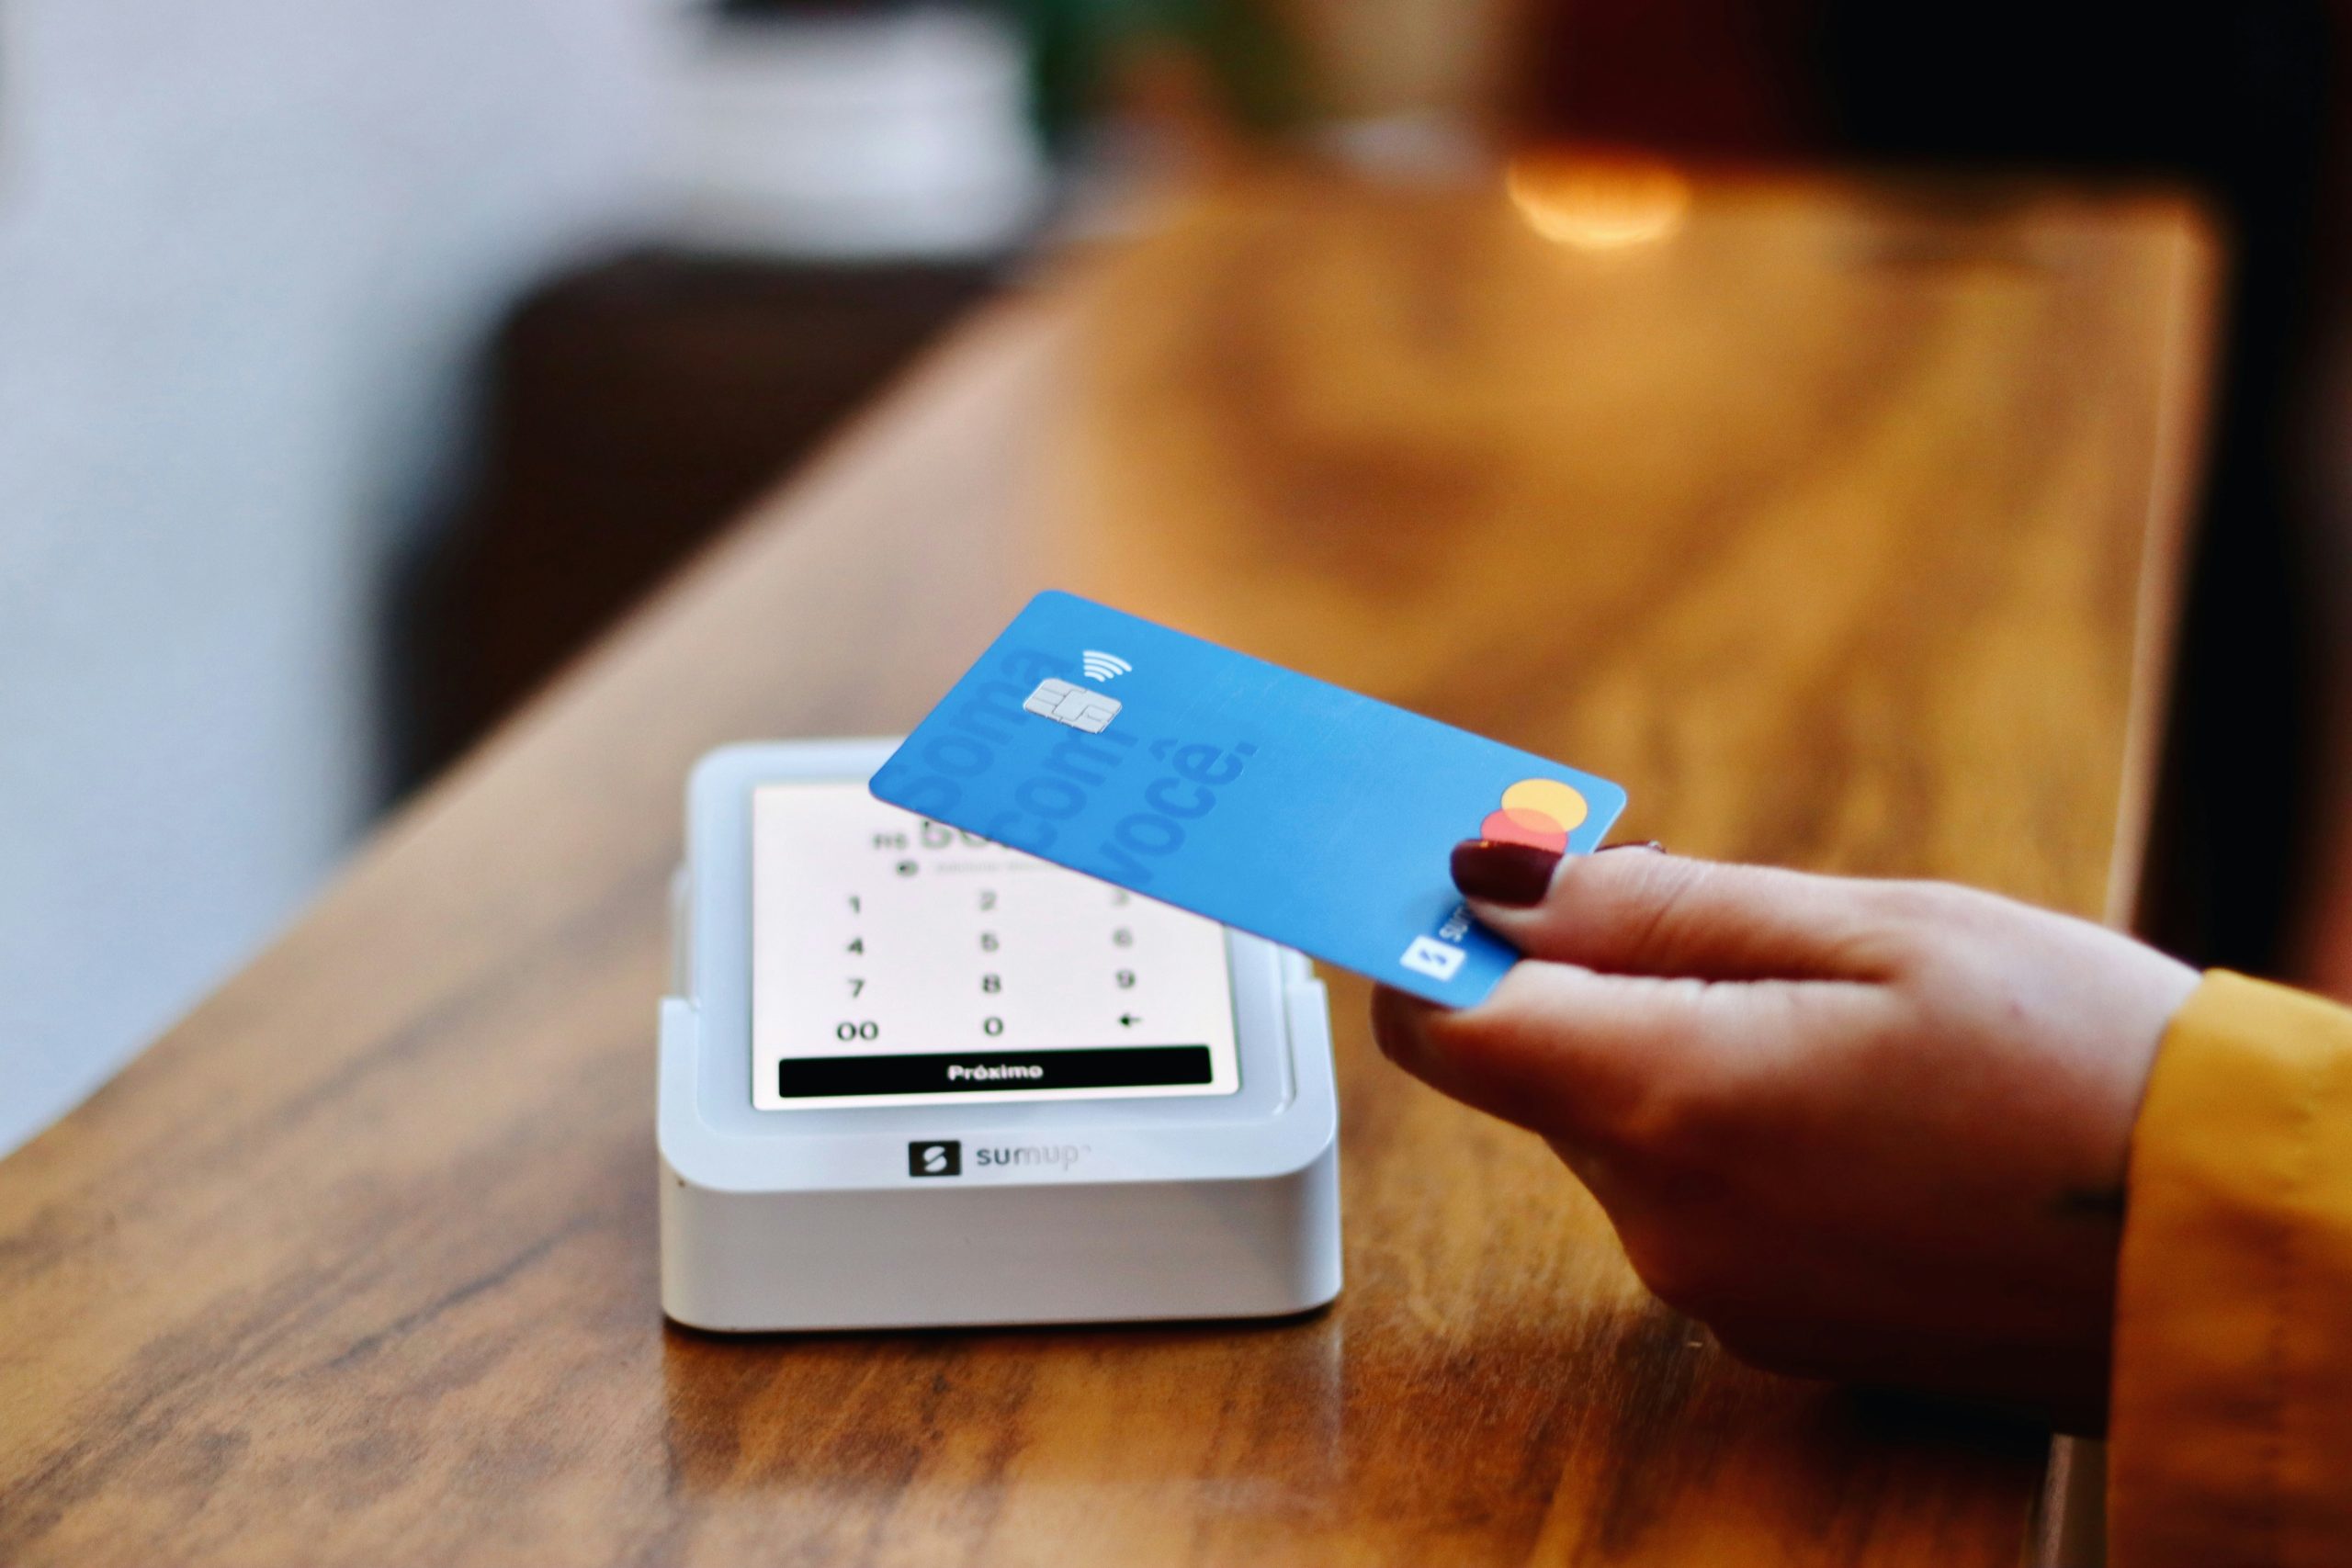
U.S. credit card debt has surged to record highs as more Americans struggle with rising costs, high interest rates, and missed payments. Here’s what the debt crisis means for households and the economy.
America’s Credit Card Debt Crisis Is Getting Worse — And Millions of Households Are Feeling the Pressure
America’s relationship with credit cards is entering a more dangerous phase.
After years of inflation, elevated borrowing costs, and growing pressure on household budgets, U.S. consumers are carrying historic levels of revolving debt while falling behind on payments at increasing rates. What once looked like resilient consumer spending is beginning to expose cracks beneath the surface, raising concerns about financial stress among middle-income households and the broader health of the economy.
The latest reporting shows that Americans collectively hold roughly $1.25 trillion in credit card debt, a staggering figure that highlights how deeply borrowing has become embedded in everyday financial survival. But the bigger warning sign may not be the amount itself — it is the growing number of consumers who are struggling to pay balances back.
As delinquencies climb and interest costs remain painfully high, many financial analysts believe the U.S. consumer may be entering a more fragile chapter.
Why Americans Are Relying More on Credit Cards
For millions of households, credit cards increasingly function less as convenience tools and more as financial shock absorbers.
The reasons are easy to understand.
Although inflation has cooled from its peak, prices for essentials such as groceries, rent, insurance, healthcare, childcare, and utilities remain far higher than just a few years ago. Wages have risen in many sectors, but not always fast enough to offset the cumulative impact of higher living costs.
As a result, consumers facing tighter budgets are often forced to bridge the gap between paychecks using revolving debt.
That shift matters.
Unlike mortgages or auto loans, credit card debt carries some of the highest borrowing costs in the financial system. Average annual percentage rates (APRs) regularly exceed 20%, meaning unpaid balances can snowball quickly into long-term financial burdens.
For families living paycheck to paycheck, carrying even a modest balance can rapidly evolve into a cycle that becomes harder to escape.
Rising Delinquencies Signal Growing Financial Stress
Perhaps the most troubling trend is the rise in missed payments.
Consumer delinquencies — borrowers falling behind on obligations — have reportedly climbed to levels not seen since the aftermath of the global financial crisis. While some economists argue that today’s labor market remains stronger than during previous downturns, the trend nonetheless points to mounting pressure inside household finances.
Historically, delinquency spikes act as early warning indicators.
When households struggle to keep up with unsecured debt such as credit cards, it often reflects broader financial fatigue. Consumers may first delay discretionary purchases, then lean more heavily on debt, and eventually miss payments as savings cushions disappear.
This process rarely happens overnight.
Instead, it builds slowly until enough households begin retrenching, weakening consumer demand across retail, travel, entertainment, restaurants, and other spending-driven sectors.
Given that consumer spending powers a large portion of the U.S. economy, signs of financial stress deserve close attention.
High Interest Rates Are Making Debt More Expensive
Another key force driving concern is the cost of borrowing itself.
The aggressive interest-rate increases of recent years dramatically changed the economics of debt.
When benchmark rates rise, variable-rate borrowing becomes more expensive — and credit cards are among the first products to reflect that shift.
For consumers already carrying balances, this creates a painful squeeze.
Even households making regular payments can find themselves barely reducing principal because interest charges absorb much of their monthly contribution.
In practical terms, a few thousand dollars of revolving debt can become far more expensive than many borrowers anticipated.
This dynamic is especially difficult for middle-income earners who may not qualify for lower-interest financial products but still face rising household costs.
Many Americans are not necessarily overspending recklessly. Instead, some are simply struggling to maintain lifestyles amid persistently expensive necessities.
The Hidden Problem Behind “Strong” Consumer Spending
At first glance, U.S. consumer spending has appeared remarkably resilient.
Retail activity, travel demand, restaurant spending, and entertainment purchases have remained surprisingly strong despite persistent economic uncertainty.
But economists increasingly debate how much of that resilience has been fueled by debt rather than income growth.
That distinction matters.
If spending is financed through expanding credit balances rather than stronger financial fundamentals, consumption can become vulnerable to sudden pullbacks.
Once borrowing capacity tightens or delinquency rates rise, consumers often shift behavior quickly — reducing purchases, delaying major expenses, or prioritizing essentials over discretionary spending.
This raises an uncomfortable possibility: some of the apparent strength in the economy may be masking deeper household strain.
For businesses reliant on consumer demand, that creates uncertainty.
Retailers, banks, lenders, and even housing-related sectors closely monitor debt trends because shifts in household finances can ripple through the broader economy faster than expected.
Banks May Benefit — Until They Don’t
At first, higher credit card interest rates can appear beneficial for lenders.
Banks earn more from revolving balances, interest charges, and fees when borrowing increases.
However, rising delinquency levels introduce risk.
If too many consumers fail to repay balances, lenders face mounting charge-offs and losses.
This balancing act explains why financial institutions carefully monitor credit quality, underwriting standards, and borrower payment behavior.
A rise in defaults does not automatically signal crisis, but persistent deterioration can influence lending standards and access to credit.
Should banks become more cautious, some consumers may suddenly find themselves facing lower credit limits, higher borrowing costs, or reduced access to financing altogether.
That tightening effect can reinforce economic slowdowns.
What This Means for American Households
For consumers, the lesson is increasingly clear: the cost of carrying revolving debt matters more than ever.
Households facing mounting balances may feel trapped by interest accumulation, especially when minimum payments barely dent overall debt.
Financial experts frequently recommend prioritizing high-interest balances, seeking lower-rate consolidation options when possible, and building emergency savings to reduce dependence on revolving borrowing.
Yet the larger story goes beyond personal budgeting.
America’s growing credit card burden reflects deeper structural tensions: higher living costs, uneven wage growth, expensive borrowing, and a consumer economy still adjusting after years of disruption.
The challenge is no longer simply spending too much.
For many households, the question has become whether incomes can realistically keep pace with the cost of modern life.
Is America Approaching a Consumer Debt Reckoning?
The U.S. economy has repeatedly defied pessimistic forecasts, and consumer resilience should not be underestimated.
Employment remains relatively strong, incomes continue growing in many industries, and households still possess spending power.
But warning signals are becoming harder to ignore.
Record credit card balances, elevated borrowing costs, and rising missed payments suggest that many families are under more pressure than headline economic data sometimes reveals.
If delinquencies continue climbing and borrowing increasingly replaces savings or wage growth, policymakers, banks, and businesses may face difficult questions about the sustainability of consumer spending.
For now, America’s credit card debt boom remains manageable.
The bigger question is whether it represents temporary financial strain — or the beginning of a more serious consumer debt crisis.
Source: https://www.wsj.com/personal-finance/credit/us-credit-card-debt-af5c7c77?mod=hp_lead_pos2



0 Comments