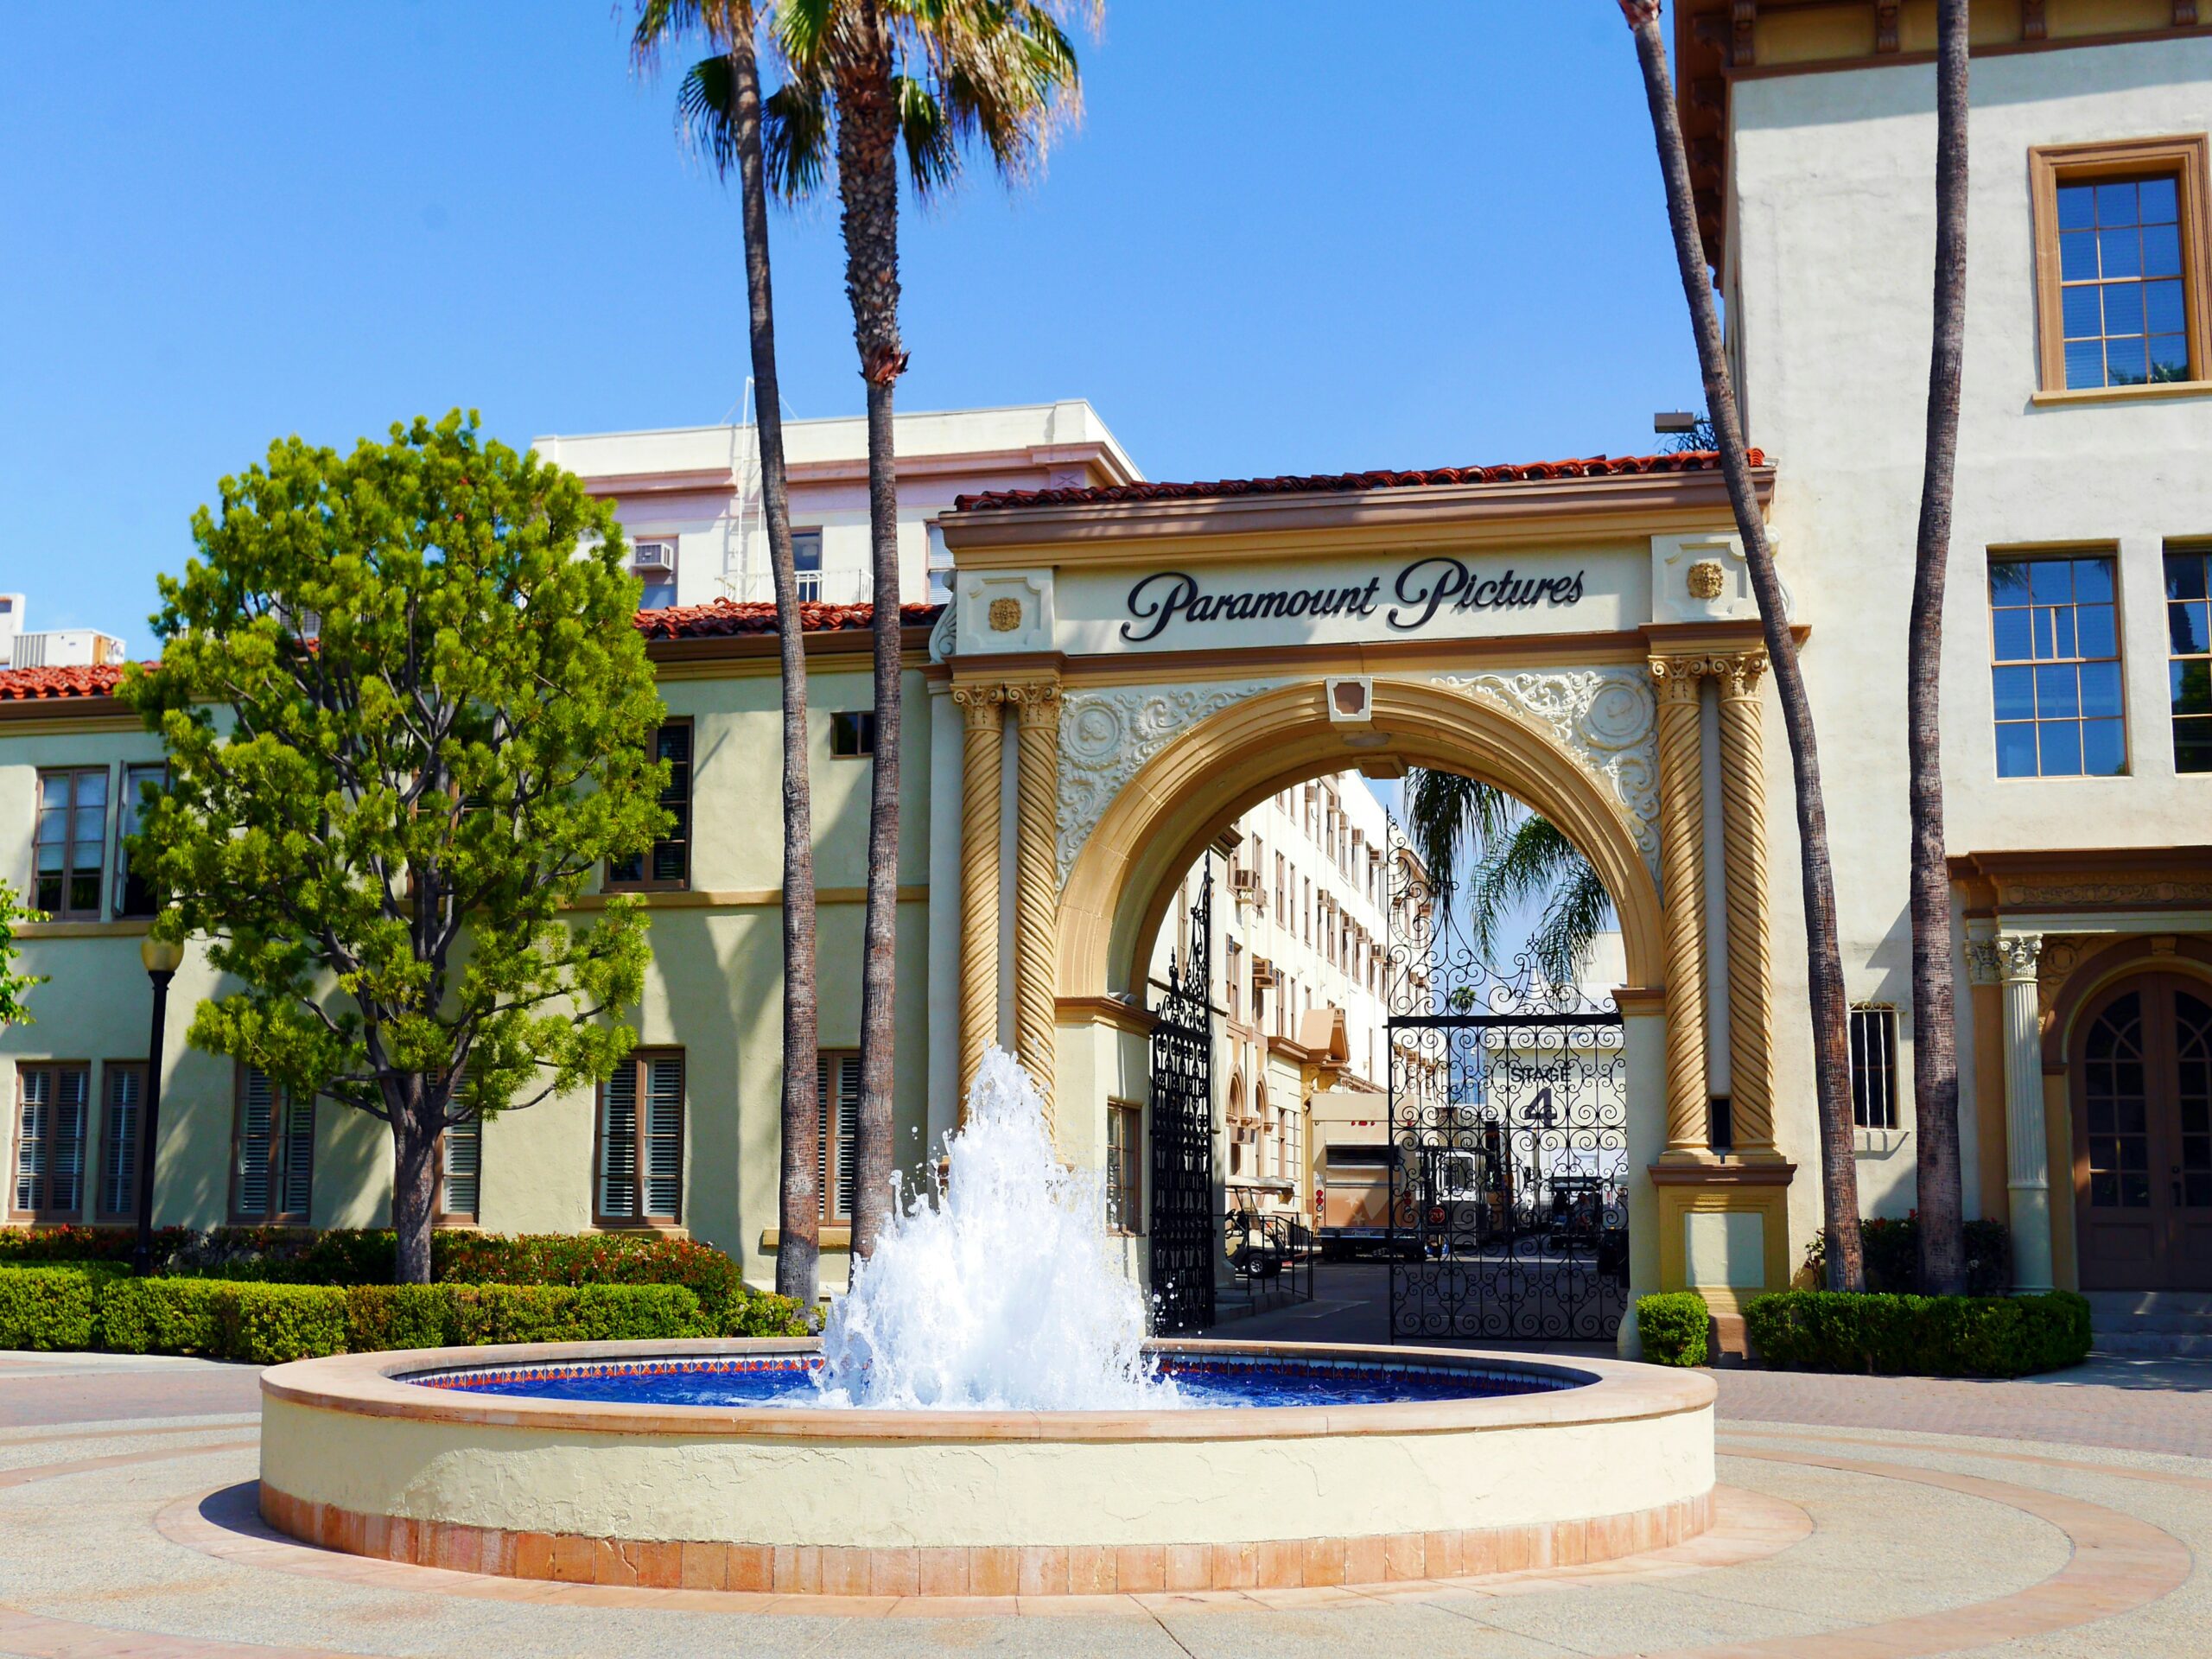
Paramount Skydance’s $52 billion debt sale to finance its Warner Bros. Discovery acquisition highlights the growing cost of corporate borrowing as interest rates and Treasury yields remain elevated.
Paramount’s Massive Debt Sale Highlights a New Reality for Corporate America
Paramount Skydance’s enormous $52 billion debt sale has become a major test for corporate borrowing conditions, demonstrating how much more expensive financing has become as interest rates and bond yields remain elevated.
The media company completed the record-setting financing as it prepares to complete its acquisition of Warner Bros. Discovery. The transaction represents one of the largest corporate financing packages ever brought to the bond market and arrives at a challenging moment for companies that need to borrow billions of dollars.
Paramount’s experience offers an important warning for corporate America: even companies with access to enormous capital markets can face significantly higher financing costs when government bond yields rise.
Paramount Had to Pay More to Borrow
Paramount Skydance's financing package included tens of billions of dollars in secured notes and term loans. According to Paramount's own announcement, the company agreed to issue multiple classes of bonds with interest rates ranging from the mid-6% range to above 9%, depending on maturity and seniority.
The financing included:
- $41.4 billion of dollar-denominated senior secured notes
- €885 million of euro-denominated notes
- $8.5 billion of term loans
- Multiple bond maturities extending from 2028 through 2066
- Some second-lien debt carrying interest rates above 9%
The numbers illustrate the price companies may have to pay when investors demand greater compensation for taking credit risk.
For Paramount, the issue is particularly important because the borrowing is connected to an enormous corporate acquisition.
Financing the Warner Bros. Discovery Deal
Paramount is using the financing to support its approximately $110 billion transaction involving Warner Bros. Discovery, including debt associated with the deal.
The acquisition would dramatically expand Paramount's entertainment portfolio and combine major Hollywood assets, streaming businesses and television operations.
But the transaction also creates a much heavier balance sheet.
Reports indicate the combined company could carry roughly $80 billion of net debt, making the success of the merger dependent not only on growing revenue but also on generating substantial cash flow and achieving significant cost savings.
That creates a difficult equation for Paramount's management.
The company must invest in streaming and entertainment while simultaneously servicing a much larger debt burden.
Rising Treasury Yields Are Making Corporate Borrowing More Expensive
Paramount's financing comes as the broader bond market has become considerably more challenging.
The benchmark 10-year U.S. Treasury yield recently reached about 5.34%, its highest level since 2002, while the 30-year Treasury yield climbed to roughly 5.69%.
Those government borrowing costs matter for corporations because corporate bonds generally trade at a premium, or spread, above comparable Treasury securities.
When Treasury yields rise, companies often have to offer higher yields to attract investors.
For highly leveraged companies, the impact can be substantial.
A difference of even one percentage point on tens of billions of dollars of debt can translate into hundreds of millions of dollars in additional annual interest expenses.
Paramount’s Bond Market Reception Raises Questions
The initial trading performance of Paramount's newly issued bonds added another layer of concern.
Some of the company's new bonds fell below their issue prices shortly after trading began. Reports indicated that the eight-year dollar-denominated junk-rated notes traded around 96 cents on the dollar after being issued at par. Paramount's stock also suffered a sharp decline during the market's reaction to the financing.
The development is significant because it shows the difference between successfully completing a bond sale and completing one on particularly favorable terms.
Paramount was able to raise the enormous amount of money it needed.
However, investors subsequently demanded higher yields in the secondary market, suggesting that some buyers considered the original pricing aggressive.
Why the Paramount Deal Matters Beyond Hollywood
The Paramount financing is not simply a story about the entertainment industry.
It provides a broader indication of how today's interest-rate environment is affecting corporate America.
For years, companies benefited from exceptionally low borrowing costs. Cheap debt helped corporations finance acquisitions, refinance existing obligations, invest in technology and return money to shareholders.
The environment is now very different.
Higher Treasury yields mean companies refinancing old debt can face substantially higher interest costs. Companies pursuing acquisitions must also determine whether projected earnings and cost savings will be enough to justify expensive financing.
This could discourage some mergers and acquisitions that would have appeared financially attractive when interest rates were lower.
Higher Rates Could Change Corporate Deal-Making
Paramount's transaction demonstrates why financing conditions are becoming increasingly important in mergers and acquisitions.
A company might identify an attractive acquisition target, but the economics of the transaction can change dramatically when borrowing costs rise.
Consider a simplified example.
A company borrowing $20 billion at 4% would pay approximately $800 million in annual interest.
At 8%, the same amount of debt would generate approximately $1.6 billion in annual interest expense.
That $800 million difference could represent a significant portion of a company's annual earnings or free cash flow.
For companies already carrying substantial debt, the consequences can be even greater.
The Credit Market Is Becoming More Selective
Despite the challenges, Paramount's ability to raise $52 billion demonstrates that investors remain willing to provide enormous amounts of capital when the potential returns justify the risks.
The problem is increasingly about price rather than access.
Investors may still finance major transactions, but they can demand higher yields, stronger protections or more attractive terms.
That dynamic puts greater pressure on corporate executives to demonstrate credible plans for increasing earnings and reducing leverage.
Paramount has outlined substantial cost-cutting ambitions as part of its strategy for the combined company.
The challenge will be delivering those savings while simultaneously maintaining investment in content, streaming platforms and other businesses that require significant capital.
What Paramount Means for Investors
For investors, the Paramount debt sale highlights an important distinction between revenue growth and financial strength.
A company can become larger through an acquisition while simultaneously becoming more financially vulnerable if the transaction requires substantial borrowing.
Investors therefore need to watch several indicators:
- Corporate debt levels
- Interest expense
- Free cash flow
- Bond yields
- Credit ratings
- Debt maturities
- Refinancing requirements
- Cost-cutting targets
- Revenue and earnings growth
Paramount's future financial performance will determine whether its enormous financing package becomes a strategic advantage or a long-term burden.
A Warning for Corporate America
Paramount's $52 billion financing is arriving at an important moment for the U.S. economy.
Corporate profits remain relatively strong, but higher interest rates, elevated energy costs and volatile bond markets are changing the financial environment for businesses. Reuters recently reported that investors are becoming more cautious about the sustainability of strong corporate profit growth as higher borrowing costs create additional pressure.
The lesson from Paramount is straightforward: large companies can still borrow enormous sums, but they may have to pay significantly more for the privilege.
That could reshape corporate strategy across industries.
Companies with strong balance sheets may continue pursuing acquisitions and expansion. More highly leveraged businesses, however, may prioritize debt reduction, refinancing and cash preservation.
The Bottom Line
Paramount Skydance's $52 billion debt sale represents far more than a massive Hollywood financing transaction.
It is a powerful example of how higher interest rates are changing the economics of corporate America.
Paramount successfully raised the money necessary to finance its Warner Bros. Discovery transaction, but the cost of that capital is substantial. With some debt carrying interest rates above 9% and the combined company expected to carry a very large debt load, management will face significant pressure to deliver its financial targets.
For the broader corporate sector, the message is equally important.
The era of exceptionally cheap money has given way to a market where investors are demanding higher returns for taking credit risk. As long as Treasury yields remain elevated, companies pursuing major acquisitions or refinancing large amounts of debt will need to carefully consider whether the expected benefits of borrowing justify the higher cost.
Paramount's experience could therefore become an important case study for the next phase of corporate deal-making.
Financial Risk Disclaimer: This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice. Investors should conduct their own research and consult a qualified financial professional before making investment decisions.
Sources
- The Wall Street Journal — Paramount’s $52 Billion Debt Sale Shows How Higher Rates Are Biting Corporate America
- Paramount Skydance — Financing Announcement
- Reuters — U.S. corporate profits and investor concerns
- Reuters — Global bond market and Treasury yields

0 Comments