Expanding insurance in Vietnam, Prudential’s report shows, could boost GDP, strengthen financial resilience, and support national development.
Insurance
has long been seen as a financial safety net against unexpected shocks. But a
new regional study suggests it plays a far broader role: as a structural driver
of economic growth, financial resilience, and long-term national development.
The
report, Beyond Coverage: The Social and Economic Impact of Insurance in
ASEAN, released by Prudential in September 2025, examines how expanding
both non-life (including health) and life insurance across six ASEAN countries, including Indonesia, Malaysia,
Philippines, Singapore, Thailand, and Vietnam (ASEAN-6), can transform economies and lives.
Insurance
as an economic engine
According
to the study, if non-life insurance coverage across ASEAN-6 rises 50 per cent
by 2050, GDP per capita could increase by up to 3.1 per cent, with total GDP
rising 2.6 per cent. For life insurance, the impact is even greater: a 50 per
cent rise in penetration could boost GDP per capita by 5.1 per cent and total
GDP by 4.4 per cent.
“These
are not abstract projections,” the report notes. “They translate into billions
of dollars in additional economic activity, stronger household balance sheets,
and more resilient businesses.”
In
Vietnam, where total insurance penetration sits at around 3 per cent of GDP, far below the global average of
6.7 per cent, the potential
is significant. A 50 per cent expansion in non-life coverage alone could lift
GDP per capita by 2.5 per cent, while a 200 per cent increase could drive GDP
growth to 10.5 per cent, equivalent to $125 billion.
Vietnam’s
rapid economic growth, expanding middle class, and rising exposure to climate
and health risks position insurance as a cornerstone of long-term resilience.
As the country pursues higher-value growth and deeper capital-market
integration, financial protection becomes not just a household need but a
national priority.
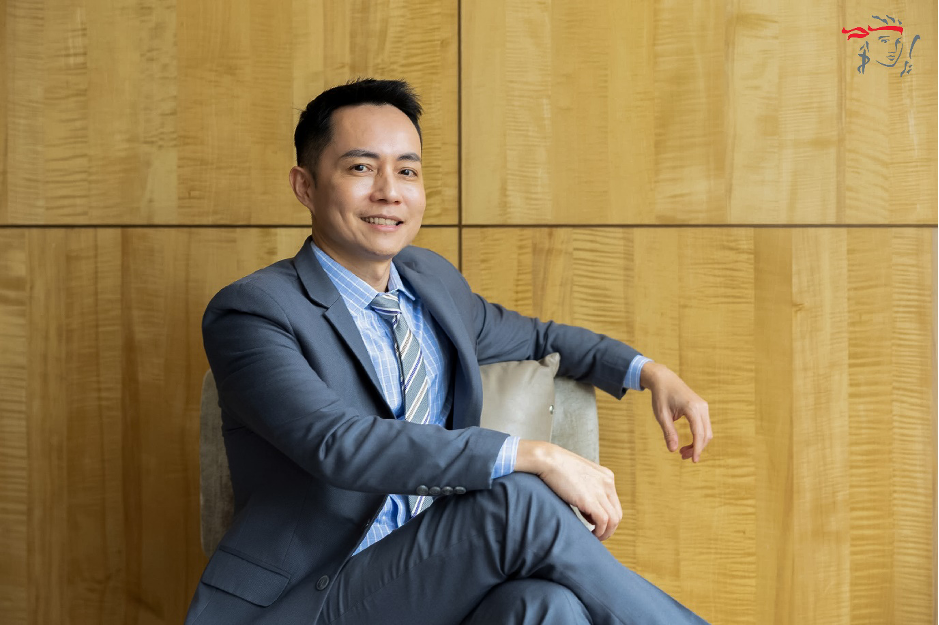
“Vietnam’s
insurance sector currently stands at a pivotal moment. With regulatory reforms,
strategic initiatives and its recent upgrade to ‘emerging market’ status, the
country is poised to rise from its low insurance penetration rate. According to
the study, a modest rise in insurance coverage of 50 per cent could add up to
$30 billion more in output by 2050. For us, now is the time to turn ambition
into actions, such as investing in diversified portfolios, developing an
interoperable health-data system and creating enhanced public-private
partnerships,” said Mr. Steven
Chan, Group Chief Government Relations and Policy Officer, Prudential plc.
Insurance
and national development goals
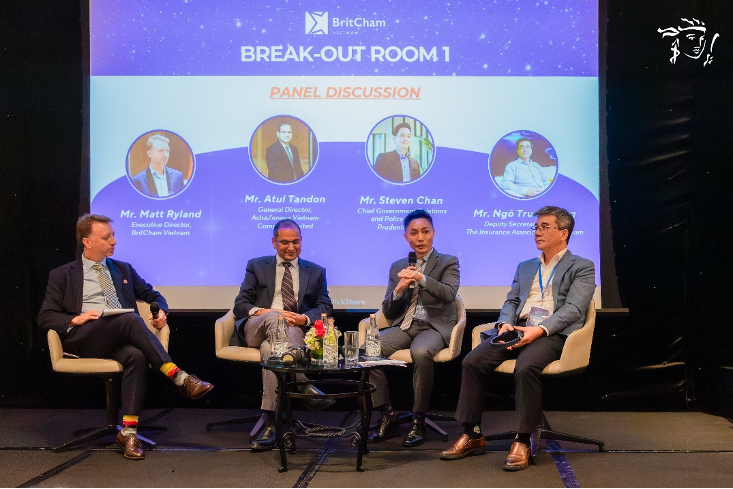
The
report links insurance directly to multiple UN Sustainable Development Goals
(SDGs). Life and health products contribute to SDG 3 (Good Health and
Well-being), while risk-mitigation products support SDG 8 (Decent Work and
Economic Growth) and SDG 9 (Industry, Innovation and Infrastructure).
Climate-risk protection and responsible investments advance SDG 13 (Climate
Action).
In
emerging ASEAN markets, insurance has also been shown to reduce poverty, keep
children in school, and improve health outcomes.
“Inclusive
insurance systems elevate entire communities, not just policyholders,” the
report emphasizes.
In
Vietnam, the life insurance industry development strategy aims for 18 per cent
of the population to participate in life insurance by 2030.
The
Beyond Coverage report reframes insurance not as a discretionary
expense but as essential infrastructure for sustainable development. For
Vietnam, where economic momentum is strong but external risks are rising, the
study provides both a timely reminder and a roadmap. Expanding insurance
participation is not just a matter of social good, it is imperative for economic growth.
–



0 Comments